
Why a subscription
Good financial planning shouldn't wait until you have a portfolio to move, or until you're ready to move it.
A strong income, a modest portfolio
Pharmacists earn well, but student debt, a mortgage and young kids often come first. The decisions you make now matter more than the balance you have. Where do I even start?
Your money is already somewhere
You've got a group RRSP, a pension, or accounts elsewhere, and you're not ready to change that. You can still get a full plan. Can I get a plan without switching?
Big decisions, no one to ask
Pension options, a first home, parental leave, incorporating, buying a store, a new job. Each one is a one-way door. Am I about to make an expensive mistake?
Tax that's bigger than it should be
RRSP, TFSA, FHSA, RESP, pension adjustments, corporate pay. Every pharmacist has more choices than time to work them out. Am I leaving money on the table?
What you get
A written plan in your first 60 days. A planner in your corner whenever you need one after that.
First 60 days: your written plan
- A cash-flow and savings system, so you know what you can spend and what goes where
- A tax plan: which accounts to use, in what order, and what to do before each year-end
- An insurance and benefits review: what your employer covers, where the gaps are, and what to do about them Including a parental leave plan, whatever your employment situation
- A retirement plan that builds on any pension you have, or replaces the one you don't
- Your existing investments, reviewed where they sit and built into the plan
Ongoing: on your schedule
- Periodic check-ins with your next step, so the plan keeps moving without any work from you
- Review meetings as often as you want them, booked around your shifts
- Decision calls whenever something big comes up A job offer, a contract, a mortgage renewal, a new baby, buying a store: we talk it through before you sign
- A tax-planning session before year-end, and a contribution calendar so no RRSP, TFSA, FHSA or RESP deadline sneaks up on you
- An annual benefits and insurance check, timed to your group enrolment or renewal
- A yearly progress report: net worth, savings rate, and how you're tracking against your goals
- I work with your accountant and lawyer, so you're not the go-between
- Unlimited email access to me, and your plan updated as your work, income, and life change
Every item above is something you can hold me to: a document delivered, a meeting held, a session booked.
Built around your work
Every plan covers the basics. Yours also covers the part that's specific to you.
Staff & hospital
Pension and group-benefit decisions, buybacks and leaves, and what to do with the income left over.
Locum & relief
Smoothing lumpy income, setting aside tax, and replacing the pension and benefits you don't get.
New grad
Student debt, a first home with the FHSA, and habits that make the next ten years easier.
Incorporated
Salary or dividends, investing inside the corporation, and a plan that covers both you and it.
Pharmacy owner
Paying yourself from the business, buying in or expanding, and planning the sale or succession of your store.
Late career
When to retire, how to draw down your savings, and which pension options to take.
See the work
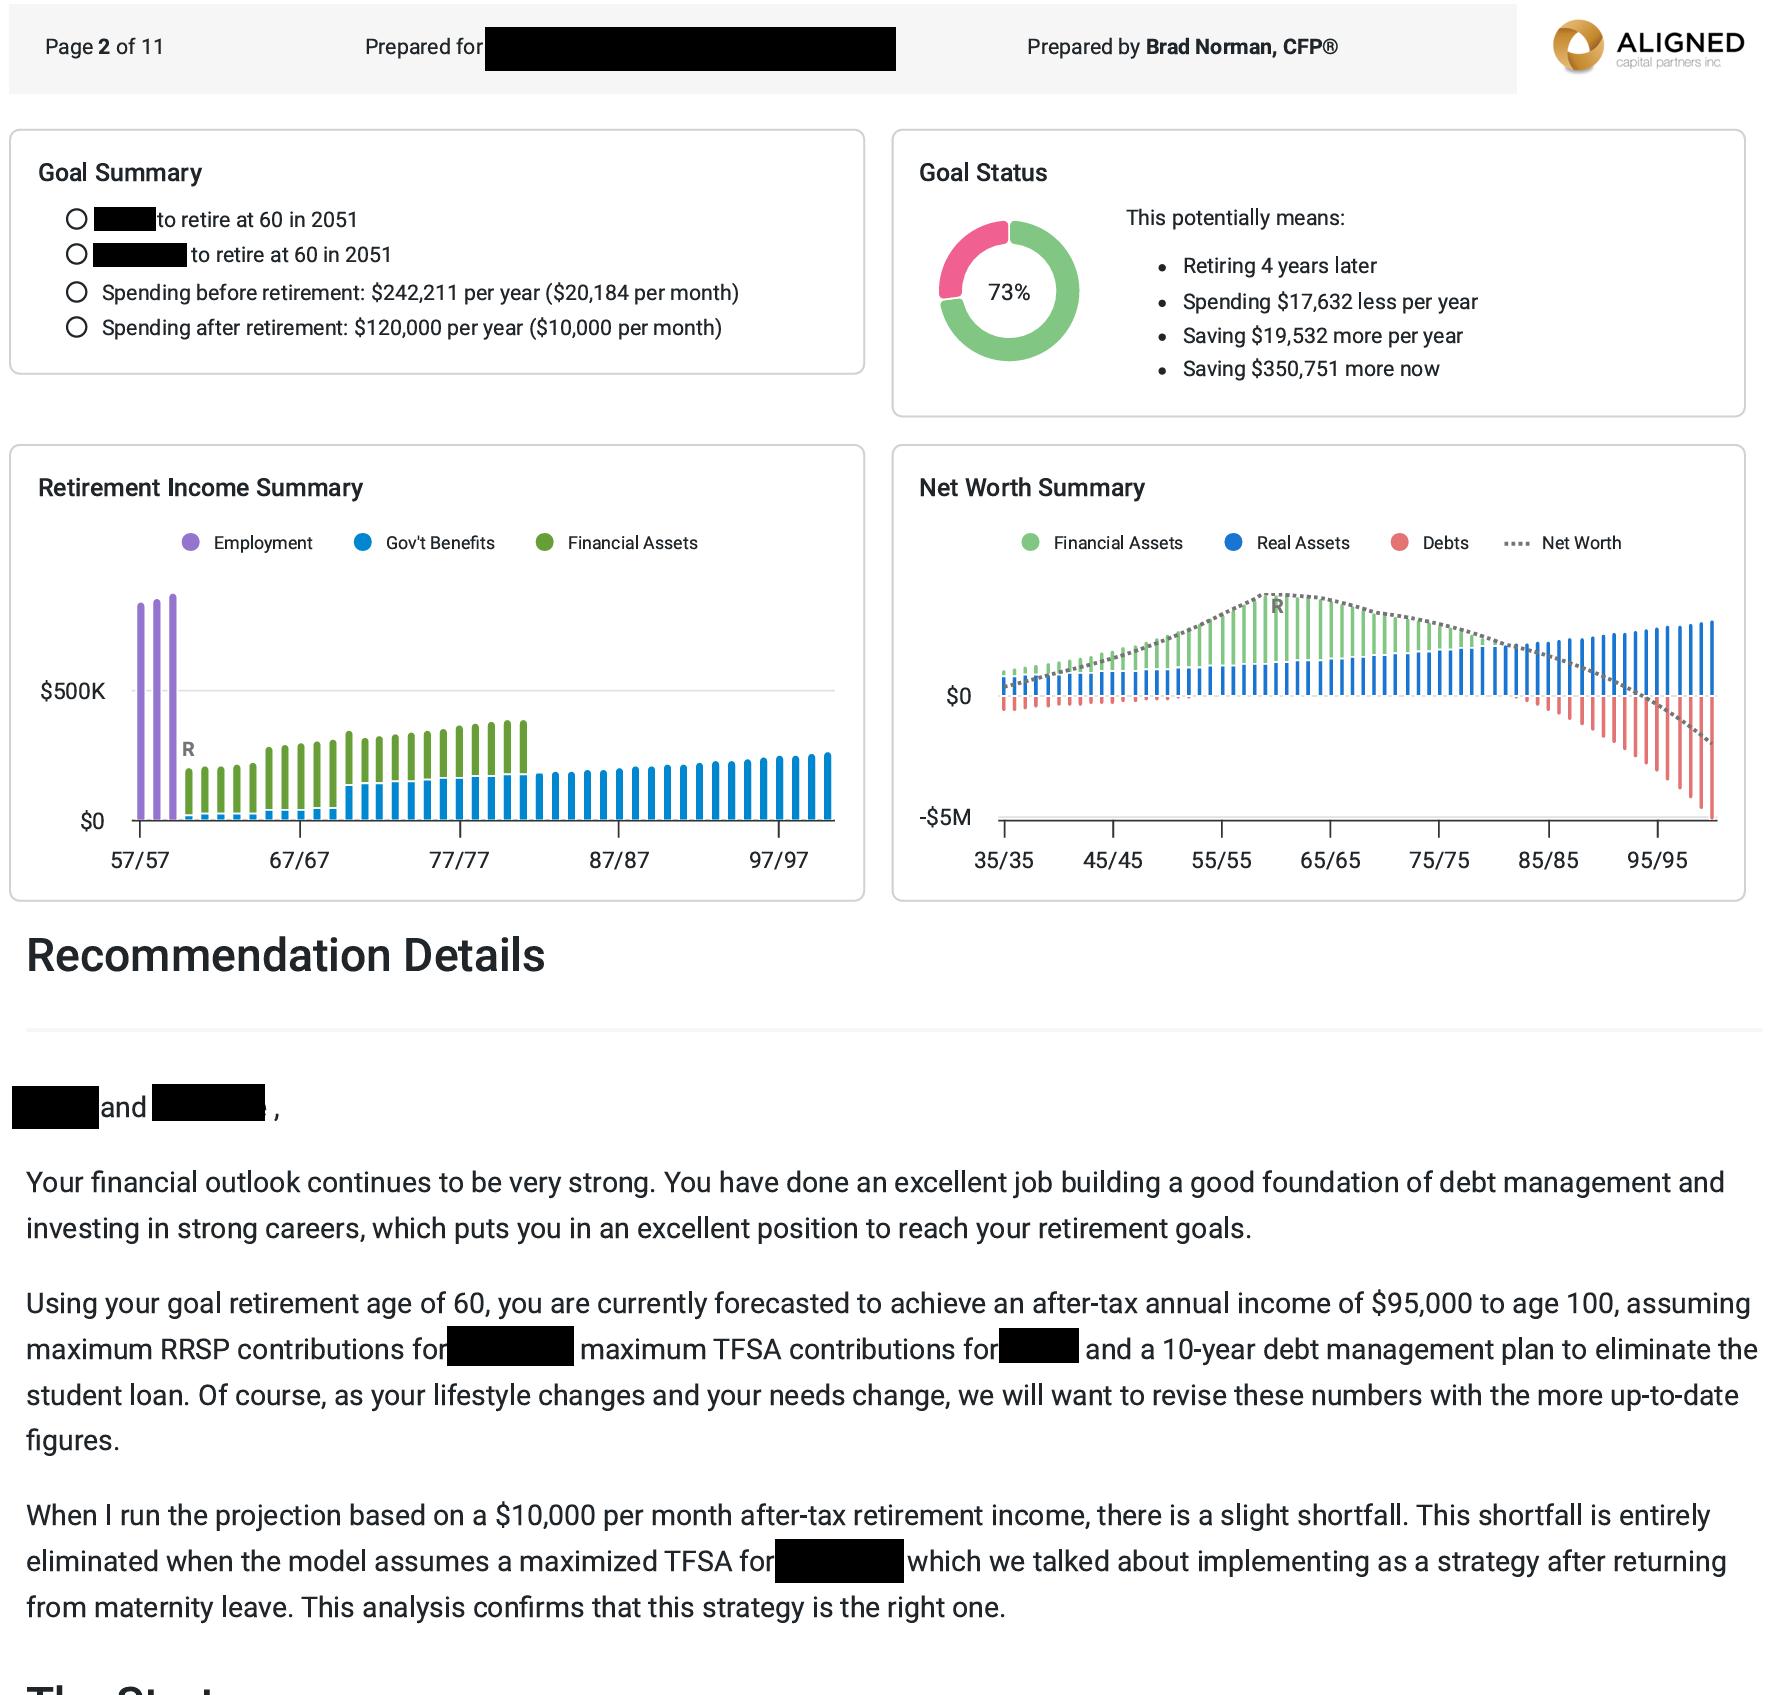
This is what a page of your plan looks like.
A page from a real client plan, with the client's details removed.
- An easy-to-read dashboard, so you know exactly where you stand
- Year-by-year metrics that show the track you're on, from today to retirement and beyond
- Clear recommendations that bridge the gap from where you are to where you want to be
One flat fee
Covers you and your spouse or partner
No asset minimums. Nothing has to move to me. Cancel anytime with 30 days' notice, you're never locked in.
A short call to confirm we're the right fit before anything starts. If it's not right for you, I'll say so.
Option 1 · Standing Order
Planning on its own
$225 a month plus tax for your household. Your investments stay where they are, or you start from zero. Everything on this page is included.
Option 2 · Managed investments
Planning plus portfolio management
I manage your investment accounts for an asset-based fee, and all of the planning on this page is included at no extra charge. You can switch from Option 1 at any time.
How I'm paid
Standing Order is a flat $225 a month plus tax, and it covers you and your spouse or partner. You're never obligated to open any accounts with me or move any assets to our firm. If you do later choose to have me manage your investment accounts, your planning is included at no extra charge and you pay an asset-based fee instead. If I recommend insurance and you live in Ontario or Newfoundland and Labrador, I can help you place it, and I'm paid a commission if you do. You're free to buy it anywhere.
About Brad
A CFP® practitioner who specializes in Canadian pharmacists.
I'm Brad Norman, a CFP® practitioner based in St. John's, working with pharmacists in Newfoundland and Labrador, Nova Scotia, New Brunswick, Ontario and Alberta (virtually or in person).
Before financial planning, I was a clinical epidemiologist (MSc in Medicine). I bring the same standard to financial decisions that you bring to drug therapy: what does the evidence say, what are the risks, and does this actually fit the person in front of you.
Most of my clients have me manage their investments, and their planning comes with it. I built this subscription for pharmacists who wanted the same planning but didn't have investments to move yet, or weren't ready to move them.
Built for you if:
- You're a pharmacist, in any role, who wants a real plan
- You don't have large investments yet, or you'd rather keep them where they are for now
- You're facing a big decision: a home, a leave, a new role, incorporating, buying or selling a pharmacy, or retirement
- You want a plan and a planner, not a product pitch
Not for you if:
- You want someone to promise lofty market returns
- You're looking for a one-time document with no follow-through (ask me about standalone plans instead)
Questions
What pharmacists ask before they book.
I don't have any investments yet. Is it worth it?
That's who this is built for. The biggest gains early on come from decisions, not portfolios: paying down debt in the right order, using the right accounts, buying the right insurance, and saving on purpose. You don't need assets for any of that.
I have a pension and benefits through work. Do I need this?
A pension is a great start, not a plan. We work out what it will really pay, how it fits with your RRSP room, what your group benefits leave uncovered, and what to do with the rest of your income.
What happens to the investments I already have?
Nothing has to move to me. I review your existing accounts where they sit, including group RRSPs and pensions, and build them into your plan.
Can I have you manage my investments later?
Yes, at any time. If you hold your investments with me, everything in your plan is included at no extra charge and you pay an asset-based fee instead of the monthly fee. There's no pressure and no deadline.
Does the fee cover my spouse or partner?
Yes. One $225 monthly fee, plus tax, covers your household. Your spouse or partner is part of the plan, the meetings, and the email access, at no extra cost.
Which provinces do you serve?
Newfoundland and Labrador, Nova Scotia, New Brunswick, Ontario and Alberta. Meetings are virtual, or in person in St. John's.
I'm a locum or I'm incorporated. Is this for me?
Yes. Locum and incorporated pharmacists are squarely in scope. Your plan covers irregular income, tax set-asides, replacing employer benefits, and both you and your corporation.
I own a pharmacy. Is this for me?
Yes. Owners are in scope. Your plan covers how you pay yourself, investing inside your corporation, financing a purchase or expansion, and planning for the eventual sale or succession of your store, alongside your personal and household finances.
I'm late in my career. Is it too late?
No. Deciding how and when to draw down your savings, and which pension options to take, matters as much as building them, and your plan covers it.
Will my plan cover parental leave?
Yes. If you're employed, we look at your employer's top-up and how EI fits. If you're self-employed, there's no automatic EI, but you can opt into EI special benefits (including maternity and parental) after a waiting period, so timing matters. Either way, your plan covers how to fund the leave.
Can we meet in the evenings or on weekends?
Meetings are booked around your shifts, so if your free time is evenings or weekends, that's when we meet.
Can my plan reflect my values?
Yes. If values-based or responsible investing matters to you, we build that into your plan's recommendations.
What happens after my plan is written?
That's when most of the work starts. I'll check in periodically with your next step, we meet as often as you want, and you can call on me whenever a big decision comes up. Your plan stays current as your work and life change, and each year you get a progress report showing how far you've come.